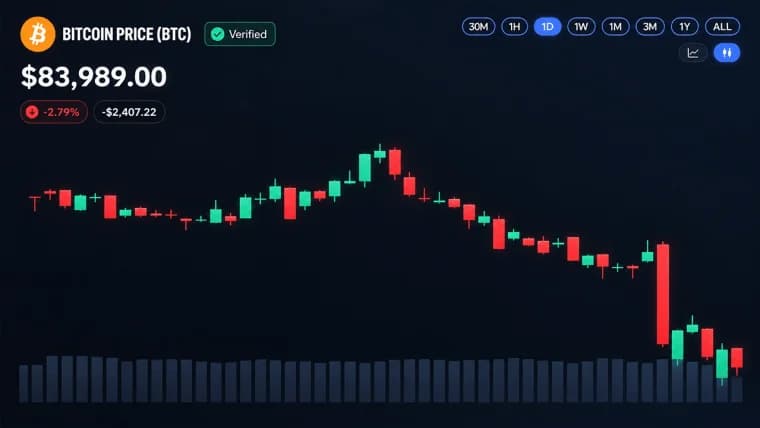
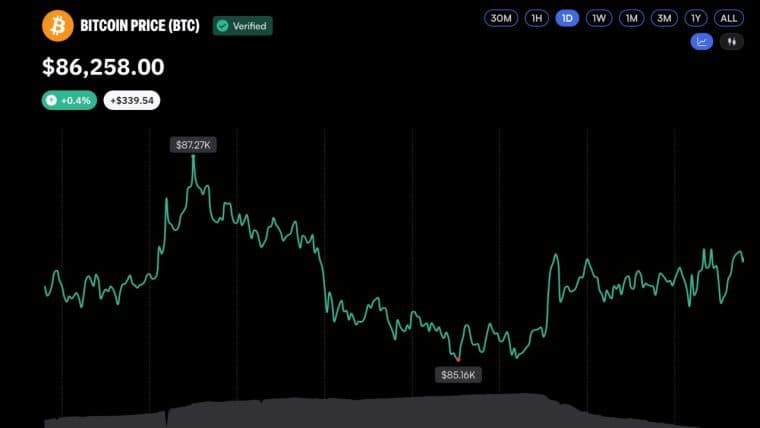
Bitcoin derivatives are flashing a split personality as bitcoin’s price trades around $84,000 on Sept. 23. Futures open interest is climbing back toward $60 billion, while options open interest has jumped above $50 billion. Calls command 60% of options positions, yet puts account for 58.2% of 24-hour options volume. Meanwhile, billions in contracts are staring at max-pain levels ranging from $60,000 to $86,000. Traders are bullishly positioned, but they’re buying plenty of insurance.
Bitcoin Derivatives Are Heating up, but Traders Want Insurance
WRITTEN BY

SHARE
Key Takeaways
- Bitcoin options open interest tops $50B as calls command 60% of positions and bitcoin’s price dipped below $84K today.
- Deribit volume flips defensive, with puts taking 58.2% of 24-hour options activity.
- Deribit and OKX show Sept. 25 max pain near $76,000 versus bitcoin at $84,416.
Crypto Derivatives Reload as Bitcoin Price Puts Traders on Edge
Bitcoin derivatives have become a rather expensive tug-of-war, with futures and options exposure rebuilding rapidly as bitcoin’s price stands around $84,000 per unit at 2 p.m. EST on Sept. 23, 2026. The strange part is what’s happening beneath that number. Before a large expiry coming Friday, calls dominate existing options positions, puts dominate fresh trading volume, and futures open interest is picking up steam. Basically, major expiration dates are scattered across max-pain levels that stretch from $60,000 to $86,000.
Bitcoin Futures Open Interest Returns Toward $60 Billion
Total bitcoin futures open interest, according to Coinglass.com stats, has climbed back toward $60 billion after spending much of June and July in the mid-$40 billion range. That remains well below the roughly $90 billion to near $100 billion peak seen in late 2025, but the rebound since August shows traders are putting leverage back to work as bitcoin pushed into the mid-$80,000 range.
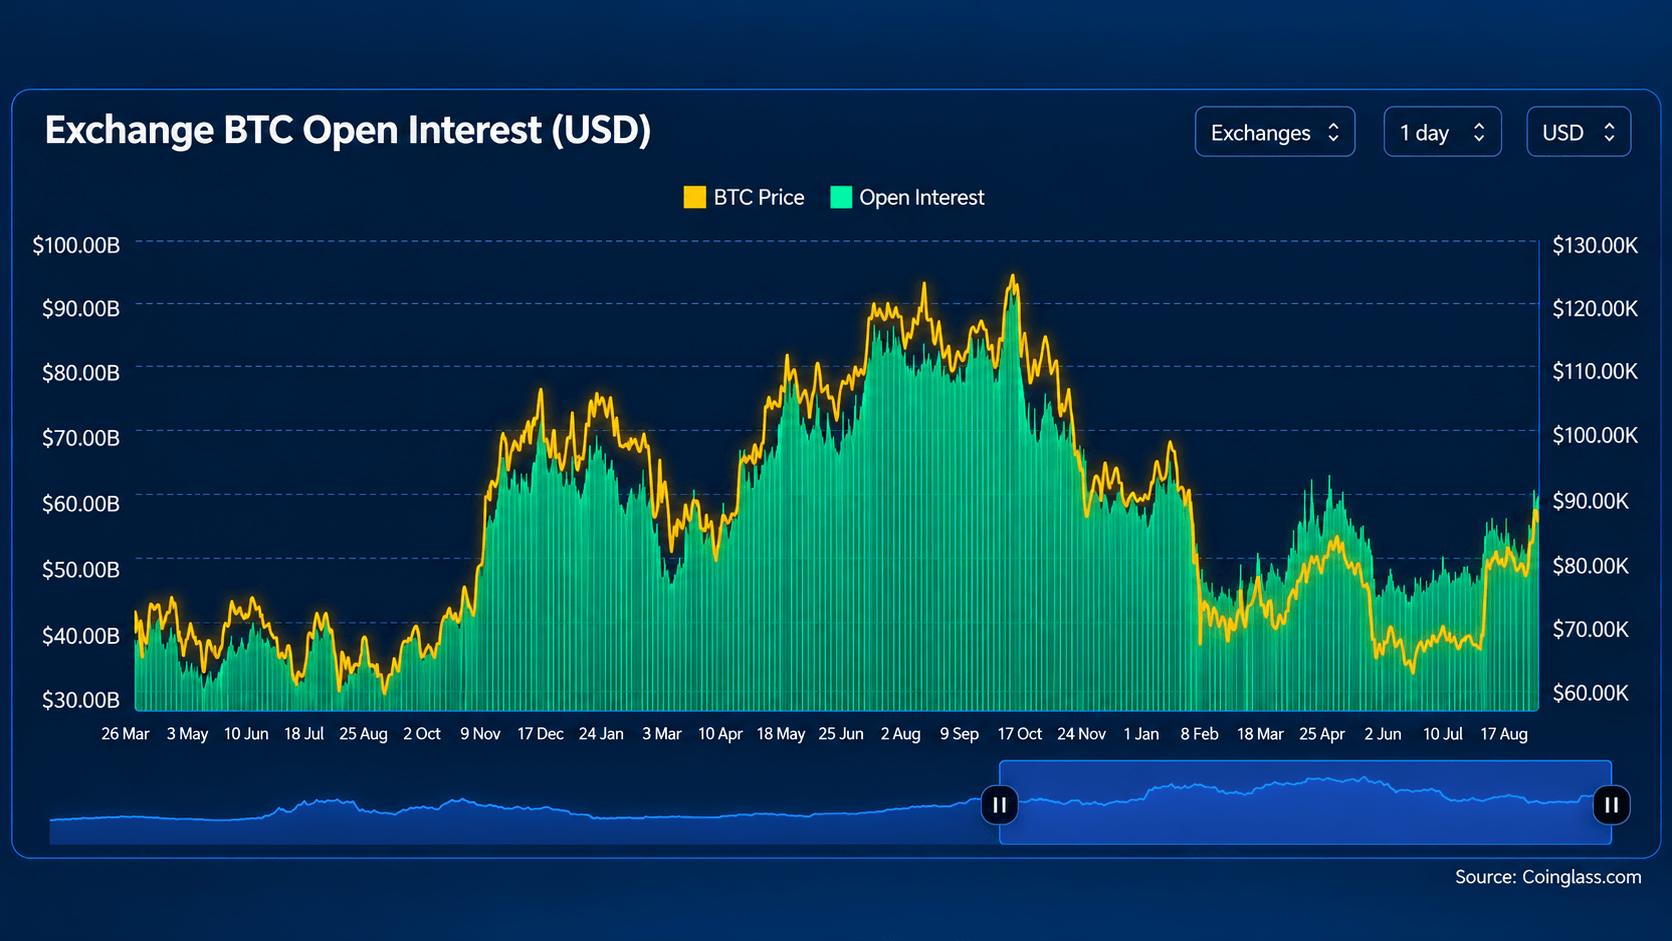
Among the top major derivatives venues, Binance carries $11.72 billion in futures open interest, followed by CME at $9.83 billion, Bybit at $5.79 billion, MEXC at $5.30 billion, and Gate at $5.21 billion. The decentralized perps exchange Hyperliquid holds $3.53 billion, while OKX accounts for $3.27 billion. Those 11 listed venues alone represent more than $49 billion in open BTC positions.
There’s a catch. Leverage has recently been getting trimmed almost everywhere. Binance open interest fell 7.13% over 24 hours, MEXC dropped 9.28%, Hyperliquid lost 12.33% and Bitunix got clobbered by 20.73%. CME slipped only 1.15%, while Kucoin was one of the few gainers, rising 3.08%. All of this happened after BTC peaked above $87,000 per coin yesterday, but has since lost 2.2% on the day.
Funding Stays Positive as Shorts Take a Beating
Funding rates offer another clue. Across Binance, Bybit, Deribit, Hyperliquid and OKX, recent annualized funding is predominantly positive, generally clustering between roughly 1% and 4%. Crypto’s largest options exchange, Deribit, has printed several larger spikes, including readings north of 5% in late September. Longs are paying for the privilege, but the market doesn’t look completely off the rails.
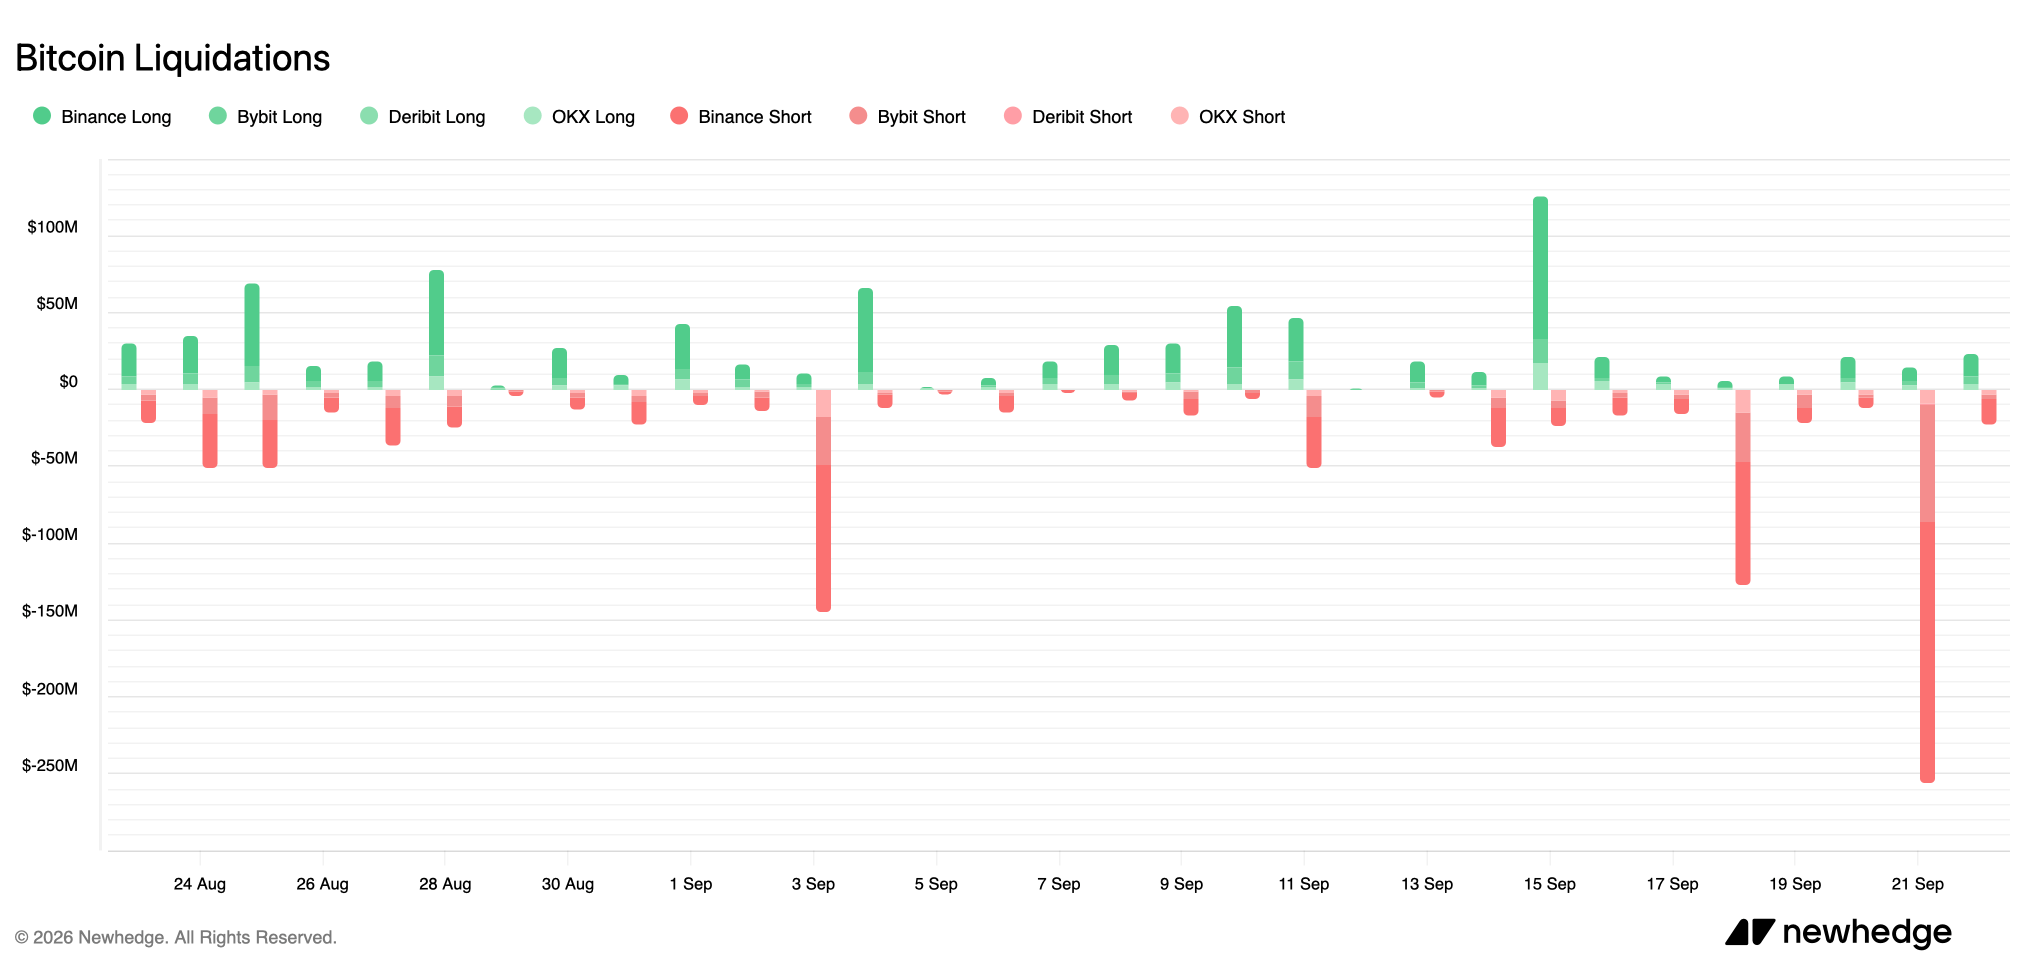
Liquidations tell the other half of the story. Sept. 21 produced the biggest short liquidation event, with more than $250 million wiped out, dwarfing that day’s long liquidations. Another roughly $130 million short flush appeared around Sept. 18. Earlier in September, the shoe was on the other foot, with about $150 million in long bets erased Sept. 3.
Bitcoin Options Open Interest Jumps Above $50 Billion
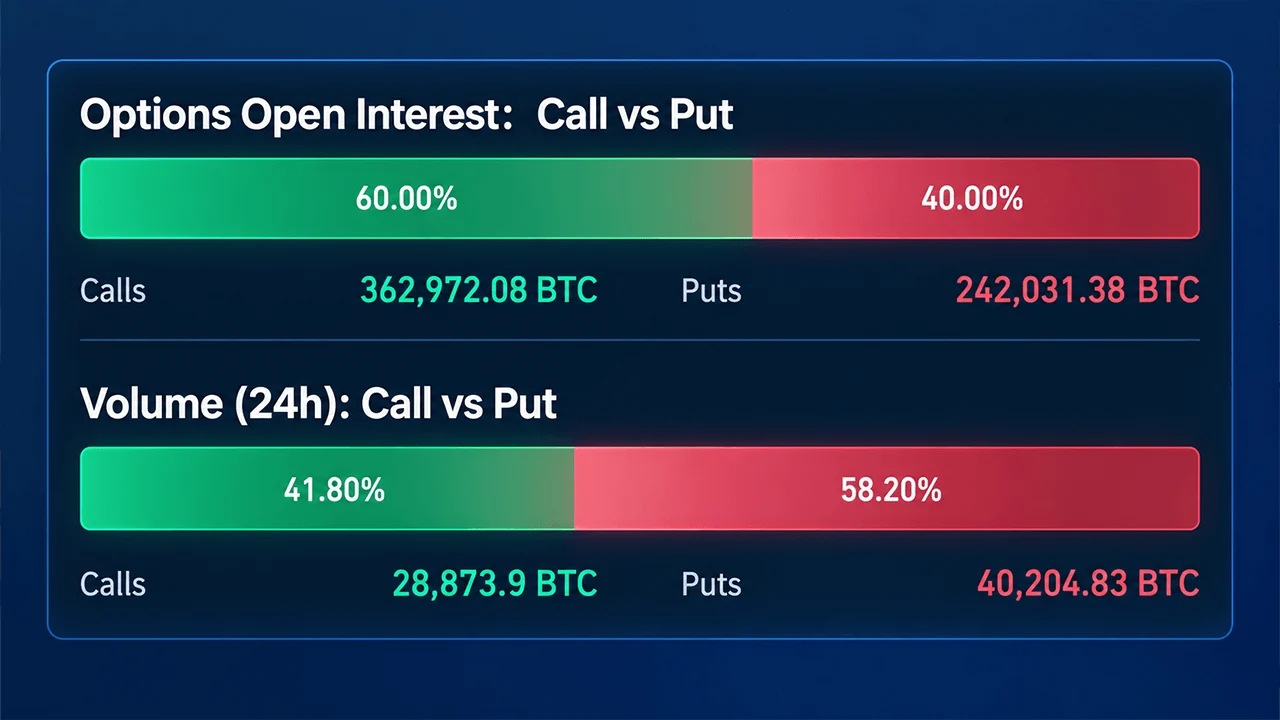
Options are where things get especially interesting. According to Coinglass metrics, total bitcoin options open interest has pushed above $50 billion this week, its highest visible level since late 2025 and sharply higher than the roughly $25 billion recorded around late June. Existing positioning leans significantly bullish. As of press time, calls represent 59% to 60% of open interest, totaling 362,972.08 BTC, against 242,031.38 BTC in puts.
On the flip side, fresh options volume is leaning the other way. Puts account for 58.2% of 24-hour volume, or 40,204.83 BTC, compared with 28,873.9 BTC in calls. In other words, traders have built a call-heavy book while recent flow shows considerably more demand for downside protection. Additionally, traders have set deep prospects for October prices, a month typically referred to as ‘Uptober,’ due to historical BTC percentage gains.
Deribit’s largest open-interest position is the Oct. 30 $95,000 call at 23,274.9 BTC, followed by the $90,000 call at 15,589.7 BTC and $100,000 call at 12,849.6 BTC. Yet the most heavily traded contract shown is Thursday’s $80,000 put. Essentially, Bullish ambition meets the insurance policy. Close to $16 billion in options is set to expire on Sept. 25, and expiry could set bitcoin’s market tone going forward.
CME Expirations and Max Pain Put $76,000 in Focus
The institutional derivatives platform CME tells a quieter story. Its bitcoin options open interest remains far beneath the late-2025 highs, when stacked positions approached $300 million and expiration-based open interest topped 70,000 contracts. Current CME positioning is spread across several expiration windows, with the largest visible portions concentrated inside roughly one to four months rather than far-dated contracts.
Then there’s max pain, the price where the greatest value of expiring options would finish worthless. For Sept. 25, Deribit and OKX both sit near $76,000, while Binance is around $80,000. Against bitcoin’s $84,416 spot price, that leaves a sizable gap just as options activity is heating up.
Farther out, the map gets messy. Deribit max pain runs near $86,000 for Sept. 26 before sliding toward $60,000 by June 2027; OKX ranges from roughly $85,000 to 72,000-75,000 across later expirations, while Binance eventually touches $70,000. With calls ruling the stockpile and puts ruling today’s traffic, bitcoin derivatives traders appear to be doing something wonderfully human, betting higher while keeping one hand firmly on the emergency brake.